All How to Build a Fintech App: Full Guide for 2026
January 3, 202610 min read

Widespread FinTech adoption is fueling growth. Half of U.S. households used online payment services (e.g., PayPal, Venmo) in 2023, and tens of millions are using digital banking and investment applications. Interestingly, 8 of the 10 most valuable FinTech unicorns are headquartered in the United States. At the same time, North America had more than 12,000 FinTech companies in 2024, leading all global regions.
If you wish to be a part of this thriving sector, now is the time for FinTech software development. Our FinTech development guide is here for you. In this article, our FinTech app development company will discuss how to develop a FinTech app, along with all the details you need to know.
Key Takeaways
- In 2024, the FinTech market was worth around $340 billion, and it's on its way to $394.9 billion in 2025 and over $1.1 trillion in 2032;
- Banking, payment, and crypto apps dominate the top lists, constituting the majority of the top FinTech apps worldwide;
- FinTech applications prioritize over 8 aspects necessary for a successful app in 2025;
- FinTech app development checklist includes 8 steps.
Fintech Application Development Market Trends
Digital currency has gone mainstream, and FinTech apps are an integral part of daily life for both consumers and businesses. Global revenues are through the roof. In 2024, the FinTech market was worth around $340 billion, and it's on its way to $394.9 billion in 2025 and over $1.1 trillion in 2032. It is fueled by investor demand and user adoption.
FinTech venture capital investment is strong (over $300 billion in global startup investment in 2024), and traditional financial players are partnering with FinTech startups to build new products. So, how to build a FinTech app? First, let's start our FinTech development guide by discussing the big trends dominating FinTech app development in 2025.
Sustained Digital Payment Growth
Mobile wallets, P2P payment apps, and instant bank transfers are becoming the norm. Bank-led P2P payment users in the United States, for example, will grow to around 191 million by 2027. New instant payment infrastructures like FedNow and open banking APIs enable seamless fund transfers 24/7.
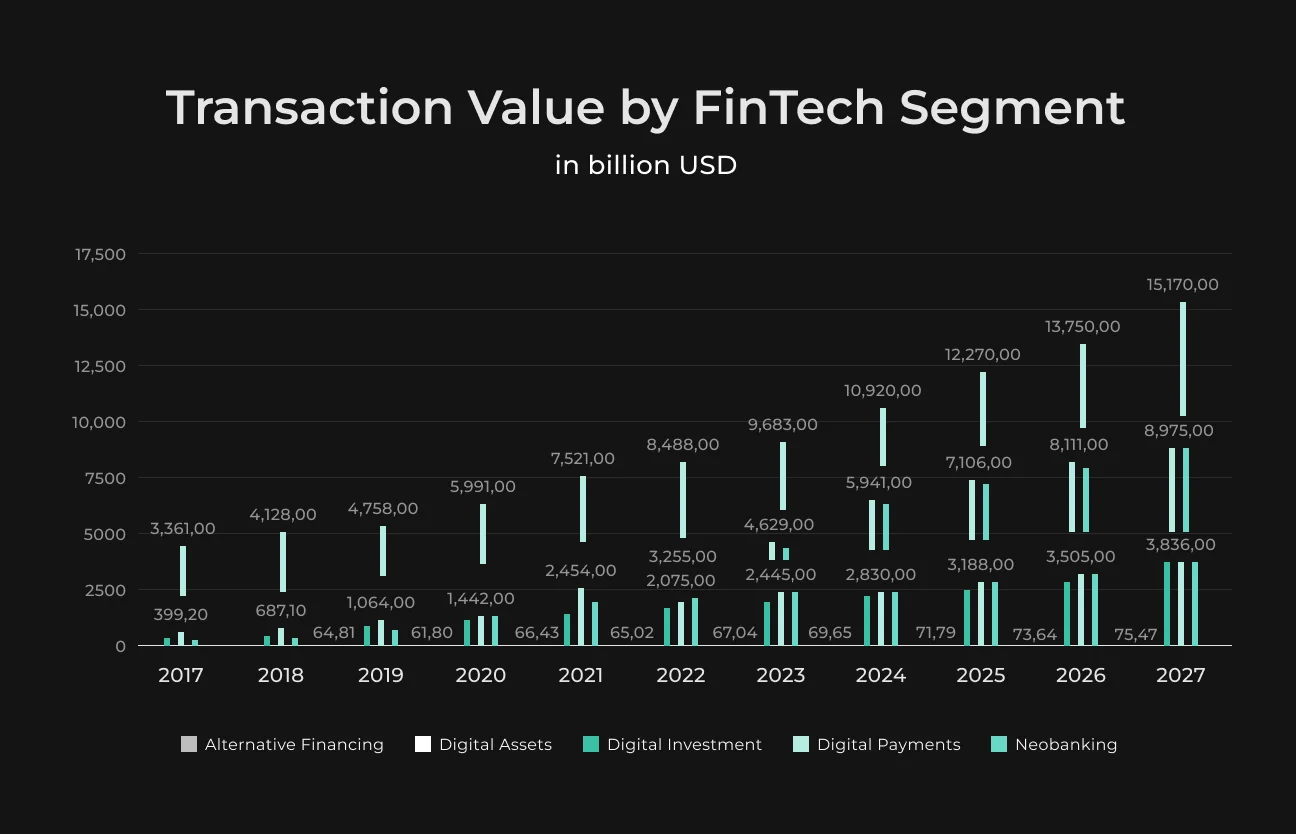
Contactless payments and QR code payments are also gaining momentum, especially in regions like Asia. FinTech apps must be ready to deal with multiple payment rails and securely process large volumes.
Banking-As-a-Service and Open Banking
Traditional banks are increasingly collaborating with FinTech companies. Open Banking initiatives (and PSD2 for the EU) require banks to expose APIs, allowing FinTech apps to securely communicate with banking functionality and data.
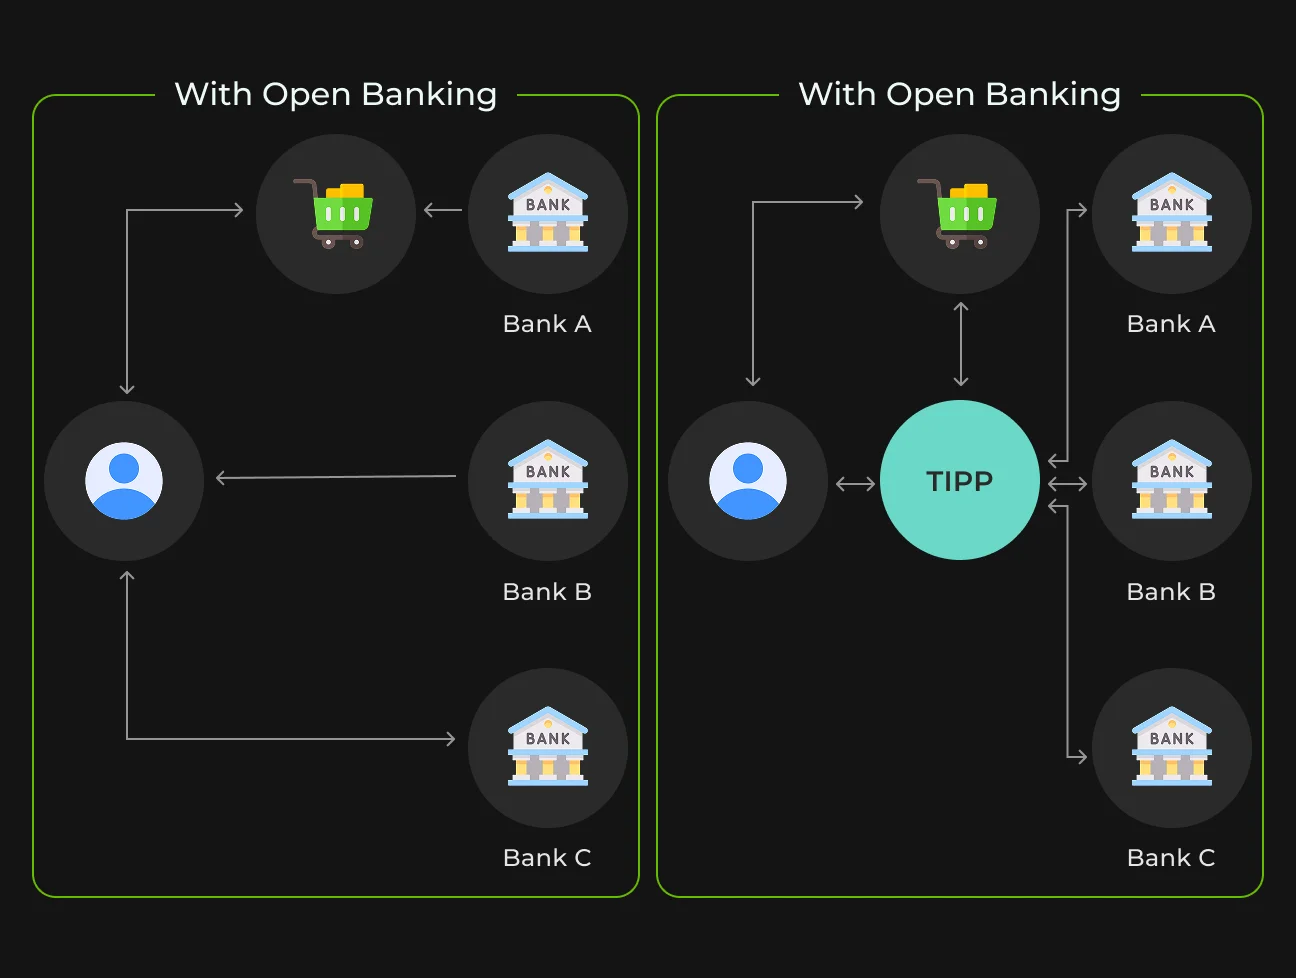
This trend enables "banking-as-a-service" platforms where non-bank entities offer financial features by piggybacking on banking infrastructure. As a FinTech app developer, using bank APIs to view account details, transaction history, or payments can improve your product a lot.
Artificial Intelligence & Automation
The AI in the FinTech space is growing 25% annually, from approximately $14 billion in 2024 to around $18 billion in 2025. Fintech applications use AI to prevent fraud, score risks, use chatbots, robo-advisors, and provide personalized financial analysis.
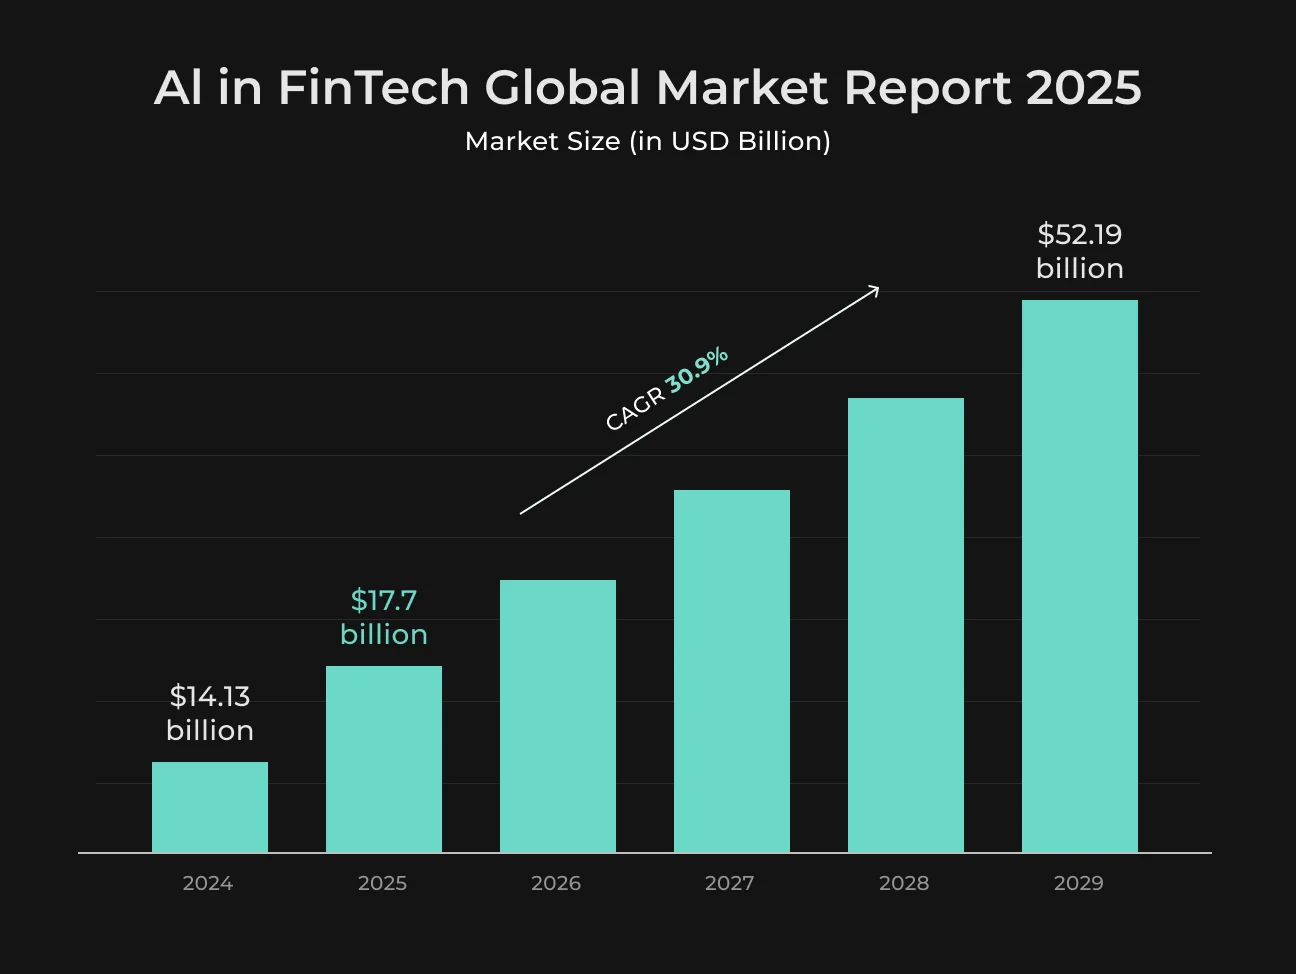
For instance, robo-advisor websites use AI algorithms to manage investment portfolios automatically, while many banks use AI to detect suspicious transactions in real-time.
Cybersecurity and Antifraud
With the increase in online transactions, the threats in cyberspace increase as well. The value of e-commerce fraud will rise from $44.3 billion in 2024 to $107 billion in 2029. U.S. fraud losses alone rose by 25% in 2024 to $12.5 billion.
Losses from AI-driven fraud and synthetic identities are already rising, with nearly half of US and UK businesses falling victim to deepfake financial scams.
Fintech apps must stay ahead with cutting-edge security technologies:
- Encryption of data at rest and in motion;
- Biometric authentication;
- AI-driven fraud prevention;
- Secure coding practices.
By the way, regulators play a big role in security standards.
Regulatory Compliance & Fintech-Friendly Policies
GDPR, CCPA, KYC/AML, payment licenses, crypto rules, and RegTech impact FinTech mobile app development. Agencies in 2025 are revising guidelines to cover digital banking, crypto holdings, and new financial models (such as buy-now-pay-later). Numerous jurisdictions are also introducing "sandboxes" and FinTech charters to promote innovation.
Main Industries for Fintech App Development
FinTech involves a wide array of industries and applications. Before starting FinTech software development, it's useful to narrow down which domain (or set of domains) your app will cater to. Below are the primary FinTech verticals in 2025 and what they represent.
Digital Banking (Neobanking)
Mobile banking apps offer the entire gamut of banking services through mobile and internet channels without any physical branch support. These are online-only banks (neobanks) or digital extensions of traditional banks. A bank app typically provides:
- Features for checking and savings accounts;
- Display of balance;
- Transfer of funds (ACH, SWIFT, P2P);
- Pay for bills;
- Remote deposit capture (scanning of checks);
- Budgeting tools, and others.
Digital banks like Chime and Revolut have drawn tens of millions of customers by providing fee-free accounts, no fees for transferring money, and competitive access to wages. Chime reported 8.6 million active members as of 2024. Revolut has hit 50 million customers globally in 2024, with 10 million in the UK. These are significant numbers.
Payment and Money Transfers
This category includes payment processors and mobile wallets (PayPal, Stripe, Square), international money transfer apps (Wise, Remitly), and P2P payment apps (Venmo, Cash App). Key features include:
- Linking a card or bank account;
- Storing funds in an electronic wallet;
- Instant alerts;
- Cross-border payments with currency exchange;
- Transaction records, etc.
Payment apps now also support contactless payments (NFC mobile pay, QR codes) and even messaging or social platform integration. Demand is nevertheless huge – digital payments are the backbone of FinTech, and 19 of the top 100 FinTech apps fall within the Payments category.
Cryptocurrency and Blockchain
This category includes:
- Crypto exchanges (Coinbase, Binance);
- Crypto digital wallets (MetaMask, Trust Wallet);
- Digital asset trading platforms (JibX, Curve DAO);
- DeFi (decentralized finance) applications (Aave, Compound).
Custom FinTech app development is especially challenging as you need:
- Integration with blockchain networks;
- Secure private key or wallet management;
- Constant adherence to the changing regulatory landscape for digital assets.
Nevertheless, demand remains high. An estimated 17% of U.S. adults have spent or invested in cryptocurrency. Moreover, worldwide spending on blockchain solutions is projected to reach $19 billion in 2024, up from $17.9 billion in 2023.
Robo-Advisors and Share Trading
Robo-advisors (Betterment, Wealthfront) use algorithms to invest customers' funds automatically into portfolios with goals and levels of risk chosen by them. They even offer reduced charges compared to traditional money planners. Meanwhile, trading stock apps (Robinhood, E*TRADE) enable consumers to trade stocks, ETFs, and other securities with minimal or no commission, and do so on a mobile platform.
Common features encompass:
- Real-time market data;
- Personalized portfolios;
- Learning content;
- AI/ML-based analysis tools, etc.
Compliance with SEC/FINRA in the US and applying risk warnings or trading halts for volatile stocks is important.
InsurTech (Insurance Technology)
Apps here provide digital-first insurance policies. A few examples include:
- On-demand insurance for short-term needs;
- Pay-as-you-drive usage-based car insurance;
- Next-gen insurance marketplaces.
Next-gen insurance companies use Big Data and AI to customize policies and premiums for every user. Key features include:
- Speedy quotes;
- Digital policy papers;
- Claims filing with picture upload;
- Live support chat (or chatbot AI);
- Third-party data integration (e.g., credit report or car history).
An insurance app must gain user trust and simplify what has traditionally been a difficult procedure.
Personal Finance & Budgeting
Examples include Mint, YNAB, or PocketGuard apps. They aggregate bank accounts and credit cards to provide users with insight into spending, budgets, and financial well-being, all within one platform. Features comprise:
- Categorization of spending;
- Reminder of bills;
- Monitoring of subscriptions;
- Goal-setting (i.e. a vacation fund);
- Credit score monitoring.
Monetization typically comes from premium features or suggestions (e.g., suggesting a better credit card).
Lending and Financing
FinTech lending apps offer alternatives to bank loans. They include:
- Peer-to-peer (P2P) lending sites;
- Micro-lending and payday advance apps;
- Mortgage/loan shopping apps;
- Buy Now Pay Later (BNPL) programs.
A lending FinTech app needs to possess strong credit risk assessment functions – most use AI-based algorithms that evaluate alternative data to establish creditworthiness instantly. The main features are:
- Loan calculators;
- Online applications with instant decisions;
- Credit bureau or bank data integration (to verify income, etc.);
- Clear repayment monitoring for users.
With growth in e-commerce and many underbanked segments around the world, digital lending apps and BNPL have tremendous demand. The peer-to-peer lending market industry is expected to grow from $218.68 billion in 2024 to $1045.37 billion by 2032.
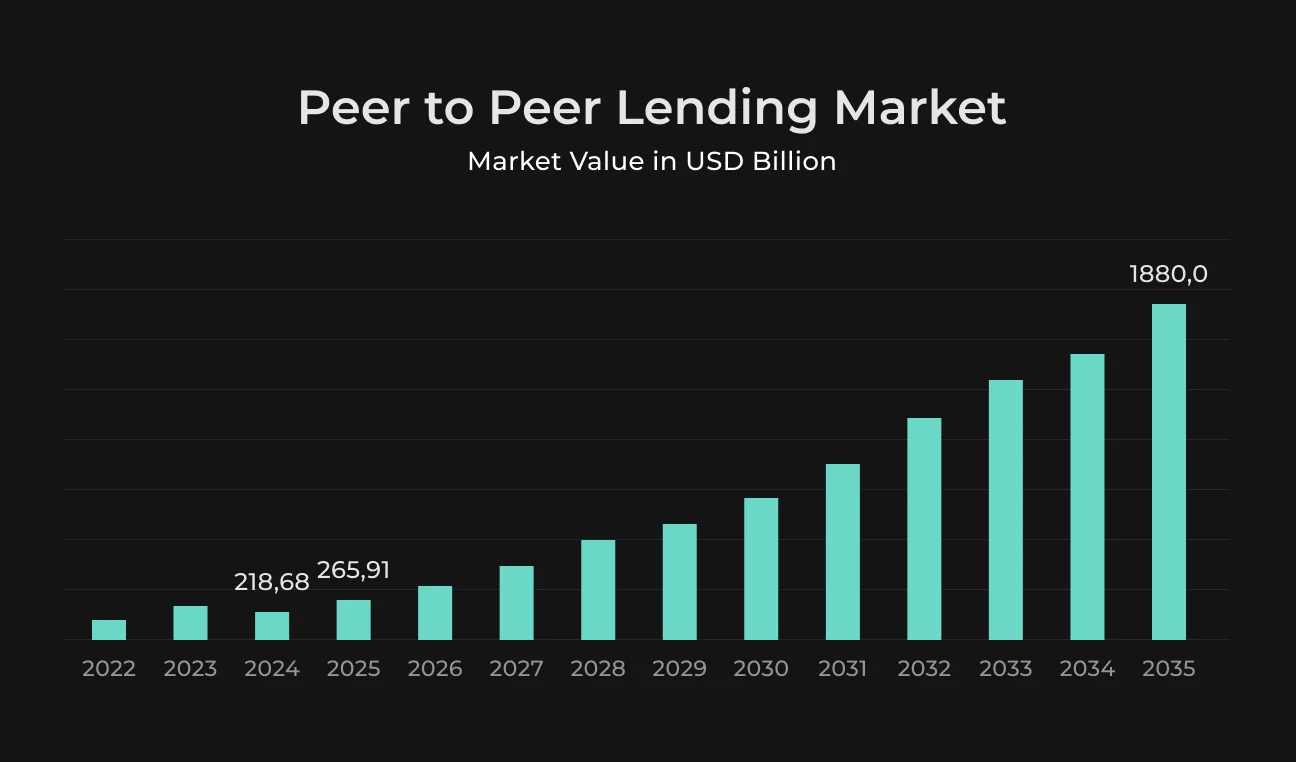
If you are going for custom FinTech app development, consider collaborating with banks or making sure that you have obtained the required lending licenses in order to run legally.
Core Features for Your Fintech Application
How to develop a FinTech app? Every FinTech application will have its own value proposition, but there are certain features and characteristics that most successful FinTech applications share. The following are the essential features you should know during custom FinTech app development.
Secure Onboarding and Account Management
Frictionless onboarding includes identity verification (KYC checks), attaching bank accounts or cards, and building user profiles. Implement features like multi-factor authentication (MFA) during sign-up and logins. This means, alongside a password, ask for a one-time SMS code or biometric login (fingerprint/FaceID).
Strong Security & Compliance Measures
Many top FinTech apps employ device fingerprinting, anomaly detection, and automatic logout after inactivity to secure accounts. Your app 100% needs:
- Encryption of data (HTTPS/TLS for data in transit, AES-256 or similar for data at rest);
- Multilayer authentication (MFA in addition to device-level security);
- Constant fraud monitoring.
On the compliance side, ensure you include necessary workflows for KYC/AML checks. We mean identity document upload and verification, sanctions list checking, etc., if your application deals with payments or financial transactions.
Integration with Banking & Payment Systems
Deep integration capability is an essential trait. For example:
- Personal finance app has to integrate with bank APIs (via aggregators like Plaid or TrueLayer) to retrieve transactions;
- Payments app integrates with card payment gateways (Stripe, PayPal SDKs) to accept transactions:
- Lending app needs to integrate with credit scoring APIs or accounting software.
In 2025, Open Banking APIs and bank-as-a-platform services make integrations easier, but you must design your app to handle API connections securely and reliably. The most critical items are:
- API authentication (OAuth tokens, API keys management);
- Webhooks or asynchronous updates handling (e.g. be notified of a payment completion);
- Graceful error handling (if a bank API is down or returns an error).
Many FinTech apps also offer integration with popular services for user convenience. We mean the ability to export data to Excel, connect with accounting apps, or log in using federated identity (like signing in with your bank or government ID). Consider using existing FinTech SDKs and middleware to speed up custom FinTech app development (there are SDKs for bank account verification, IBAN verification, etc.).
SapientPro provides FinTech mobile app development services. You can contact us anytime.
Data Analytics and Dashboards
Providing robust data analytics and presenting it through dashboards or reports is an excellent retention feature to keep users engaged. For example:
- Budgeting app can analyze transactions to show spending trends by month;
- Investment app can provide performance analytics (return on investment, risk analysis);
- Small business bank app can provide cash flow analysis or financial ratios.
On the admin/business side, it is also valuable to have an analytics dashboard. This can give insights into user behavior, most-used features, transaction levels, etc.
Alerts and Notifications
Users must be alerted instantly to important events:
- Low account balance;
- Large transaction on their card;
- Impending bill;
- Price movement in a stock they're watching, etc.
Push notifications (on mobile) and/or email/SMS alerts for important events greatly improve user engagement and trust. For example:
- Banking app should notify of any fraud activity or when a deposit clears;
- Trading app can provide price alerts or news that affects the user's portfolio.
It is also important to make notifications customizable. You must allow users to choose what they want to be notified about and how. Maybe they only want critical fraud alerts via SMS, but general updates via in-app notifications.
Fintech App Development Checklist for 2025
Custom FinTech app development is complex. Use the following checklist as a roadmap to ensure you cover all critical steps and considerations.
Step | Key Questions | Output/Deliverables |
| Market Research & Niche Selection | What financial problem are we solving? Who is our target audience? | Market research summary, user personas, competitive analysis |
| Define Monetization Model | How will the app generate revenue? Subscriptions, fees, or other? | Monetization model document, revenue projections |
| Regulatory Compliance Planning | What licenses, regulations, and data protection laws apply? | Compliance roadmap, legal consultation report |
| Define MVP Scope | What are the essential features to include in the first version? | MVP feature list, user flows, wireframes |
| Choose Tech Stack & Architecture | What backend/frontend technologies are best suited? Cloud or on-prem? | Technical documentation, system architecture diagram |
| Assemble Development Team | Do we have in-house expertise or need to outsource? What roles are required? | Team structure, vendor contracts, roles & responsibilities |
| Develop & Test the App | Are we testing for functionality, security, and user feedback loops? | Test plans, bug reports, and beta feedback summary |
| Budget & Cost Planning | What is our total budget? Have we accounted for compliance and support? | Cost breakdown, funding needs, operational expense forecast |
By following this checklist, you’ll cover the critical bases needed during FinTech mobile app development. Each FinTech project may have additional steps (for instance, partnering with banks or obtaining specific certifications), but this FinTech development guide provides a strong foundation to build upon.
Partner with SapientPro to Build Your Fintech App
SapientPro is a veteran FinTech app development company ready to be your technical partner. Our experts have hands-on experience in FinTech software development, with secure and scalable solutions implemented for banking, payments, insurance, and other domains.
With SapientPro's FinTech app development services, you have access to experienced developers, architects, and domain experts who will guide you through the process from concept to launch.
Want to know the answer to the question “How much does it cost to build a FinTech app?”
Contact us today to discuss your fintech app idea.
Build Your Fintech App With SapientPro
RELATED ARTICLES
10 min
Five Lessons from AI Failures in Production
95% of enterprise AI pilots never make it to production. We asked the founders who've seen it firsthand — here's what they said.